

Real Estate Goals for 2026: A South Florida Investor's Playbook
June 9, 2026 · 6 min read · By Onias Derilus, Broker
The best real estate investors don't just react to the market, they enter each year with specific, measurable goals. Here's how to build a 2026 real estate investment plan that actually gets executed.
Most people who say they want to "get into real estate" do not have a plan. They have a vague intention. The investors who actually build wealth through South Florida real estate enter each year with specific real estate goals: measurable, time-bound targets tied to the concrete actions needed to reach them. Here is how to build a meaningful investment plan for 2026.
Start with your "why"
Before setting any target, clarify what you are actually trying to achieve. Different goals lead to different strategies:
- Financial independence through passive income: prioritize cash-flowing rental properties in Broward or inland Palm Beach County.
- Long-term wealth accumulation: focus on appreciation markets like coastal Miami-Dade or luxury Palm Beach.
- Active income supplement: consider fix-and-flip strategies in workforce housing markets.
- Portfolio diversification: land banking in Highlands County or St. Lucie for long-term appreciation with low carrying costs.
Goal framework: the SMART model for real estate
Weak goal: "Buy an investment property in 2026."
Strong goal: "By October 2026, acquire a 2-4 unit property in Broward County with a minimum 5% cap rate and $500/month cash flow after all expenses, financed with an FHA loan at 3.5% down."
The difference is specificity. Your goal should define the asset type, location, financial criteria, financing strategy, and timeline. With those parameters set, every decision in your search has a filter.
Three categories of real estate goals
Acquisition goals: How many properties do you want to add to your portfolio? What markets? What financing structure? What minimum return criteria?
Portfolio optimization goals: Are there underperforming properties to refinance, renovate, or sell? Properties that have appreciated significantly might be good 1031 exchange candidates. Leases may need renewal, or a tenant situation may need to be resolved.
Knowledge and network goals: Which skills or knowledge gaps do you need to close in 2026? Commercial property, multifamily underwriting, and 1031 exchanges are all areas worth understanding if they are relevant to your strategy. Relationships with private lenders, contractors, and property managers matter just as much as market knowledge.
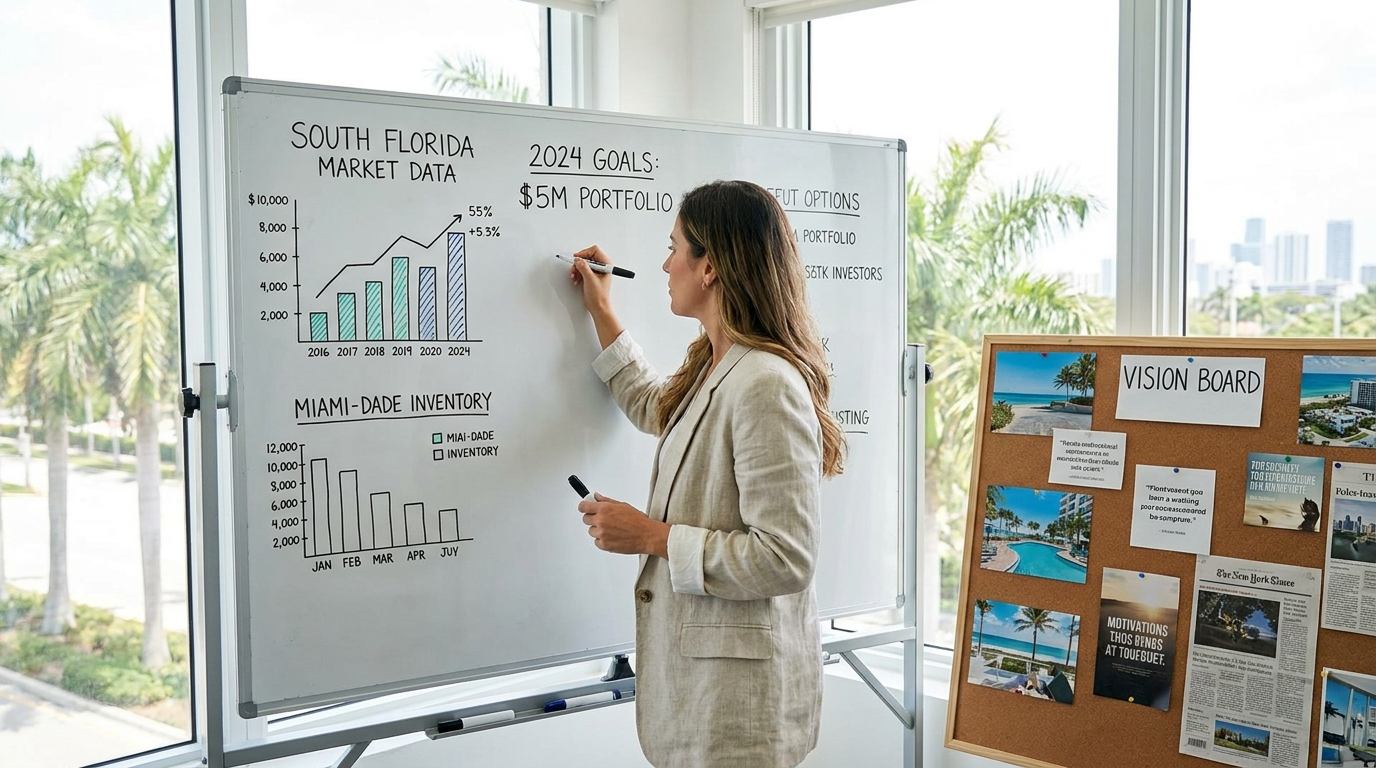
South Florida-specific opportunities for 2026
The 2026 South Florida market has specific opportunity sets worth building into your goals:
- Rising inventory in certain condo markets creates room for negotiated pricing, particularly in Broward County buildings hit by higher HOA fees and reserve requirements.
- Short-term rental market normalization has brought entry prices down in some over-built STR markets, with more realistic income projections now available for long-term rental underwriting.
- St. Lucie County growth: Port St. Lucie continues to be one of the fastest-growing cities in Florida, with fundamentals that support both appreciation and rental demand.
- Fix-and-flip in inland markets: aging housing stock in Delray Beach, Lake Worth, and western Broward offers rehab opportunities for active investors willing to put in the work.
Ready to translate your goals into a real acquisition strategy? Talk to our team at Pure Equity. We work with investors at all stages, from first-time buyers to multi-property portfolio owners, across all eight South Florida counties. Use our Rental ROI Calculator to model deals as you build your 2026 target list.
Frequently asked questions
What is a realistic real estate goal for a first-time investor in South Florida?
For a first-time investor, a realistic 2026 goal is acquiring one property with a positive cash flow of at least $200-300 per month after all expenses, including mortgage, taxes, insurance, and a vacancy reserve. Broward County and inland Palm Beach County have price points that make this achievable on a conventional or FHA loan. Define your target neighborhood and financing structure before you start searching.
How do I know if my real estate goals are too aggressive?
If your goals require financing you have not yet qualified for, repairs you cannot yet fund, or a timeline that does not account for closing and due diligence, they are too aggressive. Back each goal up with a realistic assessment of your current capital, credit, and available time. An overly aggressive goal abandoned in March does less for you than a modest goal completed by July.
Should I focus on one market or spread across South Florida counties?
New investors generally do better concentrating on one market until they understand it well. Each county, Broward, Palm Beach, Miami-Dade, St. Lucie, Martin, and the others, has different price points, tenant profiles, and local regulations. Spreading too thin early on increases the risk of missing details that matter. Once you have a deal completed and a property stabilized, expanding to a second market makes more sense.
What financial metrics should my 2026 goals include?
At minimum: target cap rate, expected monthly cash flow after expenses, cash-on-cash return, and maximum purchase price given your available down payment. These four numbers give you a filter for every property you evaluate. Add a debt service coverage ratio target if you are using investor financing rather than conventional mortgages.
Set goals you control, then track what predicts them
The reason property goals fail is almost never ambition. It is that people set outcomes they do not control and then have no idea whether they are on track until the year is over.
Buy three properties is an outcome. It depends on inventory, financing, competing buyers and timing, none of which you decide. Analyse four deals a week is an activity you fully control, and it is what produces the outcome.
So write both. Keep the outcome as the destination and set activity targets as the thing you actually manage. Then review the activities weekly and the outcome quarterly, because activities are correctable and outcomes are not.
Leading and lagging indicators, applied to property
Every property goal has both, and tracking only the lagging one is why people discover in November that the year has not worked.
- Acquisition. Lagging: properties bought. Leading: deals analysed, offers written, lenders spoken to.
- Cash flow. Lagging: monthly net. Leading: vacancy days, maintenance spend, rent collected on time.
- Selling. Lagging: sale price achieved. Leading: showings booked, feedback received, days on market against the local average.
- Agent production. Lagging: closings. Leading: conversations had, appointments set, listings taken.
Pick one leading indicator per goal and track it weekly. One tracked properly beats five tracked occasionally.
Include the defensive goals nobody writes down
Growth goals get all the attention, and the goals that keep you in the game are protective and rarely written.
Build the reserve to a defined number of months of expenses per property. Review insurance annually rather than accepting the renewal, since premiums in this state move enough to justify shopping. Get the wind mitigation report done where one is missing. Read the reserve study on any condominium you own, and attend the budget meeting.
None of that appears on a vision board and all of it prevents the events that end property plans. A year where you added no properties but built six months of reserves is not a wasted year.
Ground the numbers in your actual market
Goals set against national averages fail on contact with a specific county, so use local figures from the start.
Median asking prices currently run about $599,000 in Miami-Dade, $480,000 in Palm Beach, $410,000 in St. Lucie, $390,000 in Broward, $309,000 in Highlands and $274,900 in Okeechobee. Days on market runs from about 91 in Port St. Lucie to 206 in Highlands.
Those figures determine what is realistic. A goal to acquire and exit within a year is achievable in Port St. Lucie and close to impossible in Highlands, where the average sale alone takes most of it. Set the target against the market you are actually in.
Review quarterly, and be willing to change the goal
Annual goals with no checkpoints are wishes. Quarterly review is frequent enough to correct and infrequent enough not to become noise.
At each review ask three things. Did the activities happen. If yes and the outcome did not follow, is the activity the wrong one. And has anything changed in your circumstances or the market that makes the goal wrong rather than merely behind.
That last question matters. Persisting with a goal that no longer suits your situation is not discipline, it is inertia, and property decisions are expensive enough that changing your mind deliberately is a strength.
Write down what you will not do
Most goal setting is additive, and in property the constraints are what keep a plan intact.
Decide in advance the things you will decline regardless of how attractive they look in the moment: a maximum price, a minimum reserve you will not dip below, property types you will not take on, and counties you will not buy in because you do not know them. Writing those down while you are calm is the point, because the moment you need them you will not be.
This is also the discipline that makes the walk-away possible. A deal that fails your own written rule is easy to decline; one that only fails a vague feeling is not.
More common questions
How ambitious should a first year goal be?
Modest on outcomes and demanding on activities. One property acquired carefully teaches more than three acquired badly.
Should I focus on one county or several?
One, until you know it properly. Knowing one market well beats knowing eight vaguely, and it is the only way to recognise a good price without asking someone.
What metrics belong in the goals?
Cash flow per property, reserve months held, and one leading activity indicator. Portfolio value is a poor goal because you do not control it.


