
South Florida
Mobile Homes with Land for Sale in Florida
Mobile and manufactured homes on owned land, affordable homeownership without lot rent in Central and South Florida.
Get Listings Alerts
Be the first to know when a new mobile homes with land listing hits the market in South Florida.
Browse
Mobile Homes with Land in South Florida
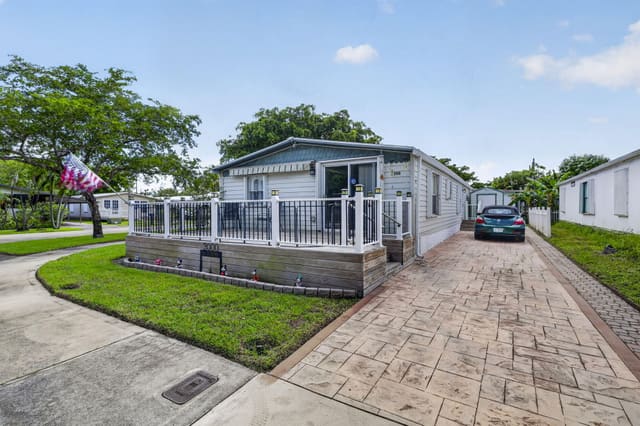
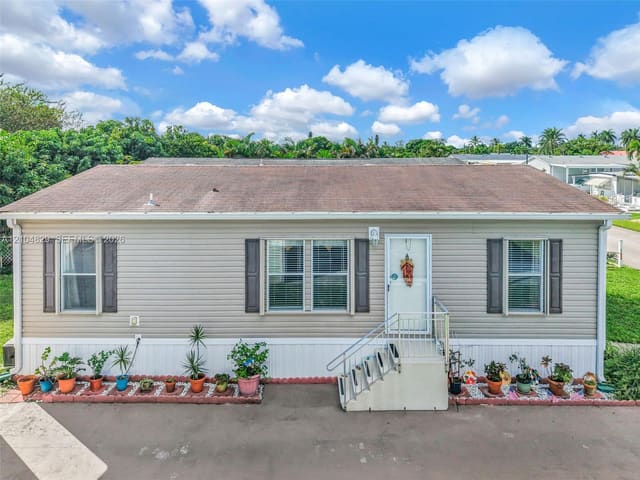
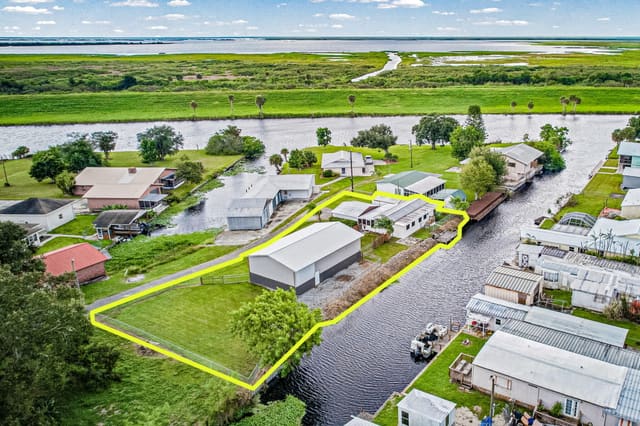
Stay Ahead of the Market
Tell us what you're looking for and we'll send matches as they hit the market.
Explore by County
Featured Communities
Mobile Homes with Land in South Florida
Mobile Homes with Land: What to Know
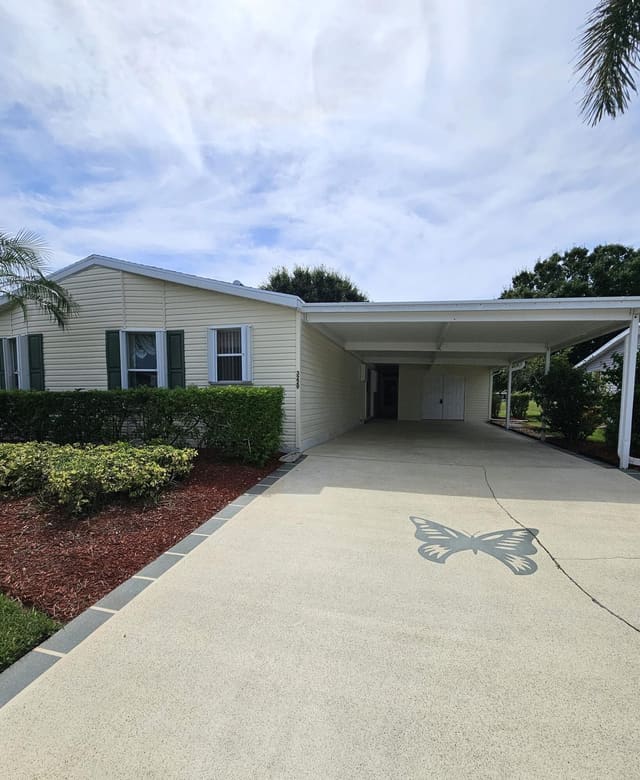
A mobile home with land means a manufactured or mobile home sitting on a parcel the owner holds in fee simple, not a unit rented in a 55+ or family park where you pay monthly lot rent. The distinction matters more than most buyers expect. When you own both the home and the dirt under it, you are buying real property: it can be financed with a conventional, FHA, VA, or USDA mortgage, it can build equity, and in many Florida markets it appreciates with the surrounding land rather than depreciating like a vehicle. Park homes, by contrast, leave you exposed to lot-rent increases and give you little to sell when you leave. For first-time buyers, retirees on fixed incomes, and investors hunting affordable cash-flow, owning the land is the difference between a depreciating box and a real estate asset.
The most active markets for these properties sit in Florida's inland counties. Okeechobee, Highlands, and St. Lucie carry deep inventory of manufactured homes on acre and half-acre lots, often with room for a workshop, an RV, or a few animals. Prices there run well below the coastal metros, which is exactly why the segment draws buyers priced out of Palm Beach or Broward. You also see manufactured homes on land scattered through DeSoto, Glades, and rural Martin County, frequently on parcels large enough to add a second dwelling or detached garage. Because zoning in these areas tends to be agricultural or rural-residential, restrictions are looser and the cost per acre is a fraction of suburban land.
Title is where this category gets technical, and getting it wrong can stall a sale. A manufactured home in Florida starts life with a HUD certificate of title, the same kind of document a car carries, issued by the state. To be financed and taxed as real property rather than personal property, that title has to be retired, a process that surrenders the HUD title and permanently affixes the home to the land on the deed. Lenders almost always require this; without it, you are limited to chattel loans at higher rates and shorter terms. Ask early whether the title has already been retired. If it has not, confirm the home is on a permanent foundation, sits on land the seller actually owns, and that the paperwork can be completed before closing. A 1976-or-later build date matters too, since HUD-code homes predating that cutoff are hard to finance and harder to insure.
Beyond title, run the same diligence you would on any rural parcel. Most of these homes rely on a private well and a septic system rather than municipal utilities, so verify the well produces clean, adequate water and that the septic drainfield is sized and permitted for the home. County health department records and a septic inspection are worth the cost. Check the flood zone, because large stretches of the interior sit in or near FEMA flood areas, and a home in a high-risk zone needs flood insurance that can rival the mortgage payment. Confirm legal, year-round road access (not just a worn path across a neighbor's land), and ask whether power is already connected or whether you will pay to run a line. Tie-downs and anchoring to current Florida wind-zone standards also affect insurability after recent storm seasons.
On cost, the appeal is straightforward. A newer manufactured home on a usable acre in Okeechobee or Highlands can sell for a meaningful discount to a comparable site-built house, and the land component gives you something that holds value even if the structure ages. Financing typically asks for a smaller down payment than raw land does, since the home is collateral, and USDA loans can reach zero down in eligible rural areas. Watch the long-term carrying costs, though: older homes cost more to insure, may need roof or HVAC work, and can face higher premiums in wind-prone counties. Budget for inspection, a survey to confirm boundaries and setbacks, and any repairs needed to satisfy the lender's appraisal.
Pure Equity works these inland markets directly and knows the practical hurdles, from title retirement to septic permits to which lenders will actually close on a manufactured home. We help buyers separate genuine fee-simple opportunities from park homes dressed up to look like land deals, line up financing that treats the property as real estate, and coordinate the inspections and surveys that protect you before closing. If you are weighing a mobile home with land anywhere from St. Lucie out to Okeechobee and Highlands, reach out and we will walk the specifics of any parcel with you.
Questions
Mobile Homes with Land: Frequently asked questions
Can I get a regular mortgage on a mobile home with land?
Yes, if the home qualifies as real property. The manufactured home must be on a permanent foundation, built in 1976 or later, and have its HUD title retired so it is taxed and recorded as real estate. Then conventional, FHA, VA, and USDA loans all apply. Without title retirement you are limited to higher-rate chattel loans.
What is the difference between this and a home in a mobile home park?
In a park you own only the structure and pay monthly lot rent on land someone else controls, which means rent hikes and little resale value. With a mobile home on its own land you own both, build equity, can finance with a mortgage, and the parcel can appreciate. Owning the land is the key financial advantage.
Do these properties usually have well and septic or city utilities?
Most mobile homes on land in Okeechobee, Highlands, and rural St. Lucie rely on a private well for water and a septic system for waste, not municipal service. Verify the well yields clean, adequate water and that the septic is permitted and sized for the home. County health department records and an inspection confirm both before you buy.
What does retiring the HUD title actually involve?
Title retirement surrenders the manufactured home's HUD certificate of title (similar to a vehicle title) and permanently attaches the home to the land on the deed, converting it to real property. Florida requires the home be on a permanent foundation and the owner hold the land. The process is usually handled at or before closing and is what lets a lender finance it.
Are mobile homes with land harder to insure in Florida?
They can be, especially older homes in wind-prone inland counties. Insurers look at the build year, roof age, foundation, and tie-down anchoring to current Florida wind-zone standards. Homes built after 1994 with updated anchoring and roofs are easier and cheaper to cover. Get an insurance quote during diligence, since premiums can be a major carrying cost.
Why are Okeechobee, Highlands, and St. Lucie the top markets for these?
Those inland counties combine low land prices with rural and agricultural zoning that allows larger lots, outbuildings, and often animals. Buyers priced out of the coastal metros find usable acreage there at a fraction of the cost. Inventory of manufactured homes on owned land is deepest in these counties, which is why most fee-simple deals turn up there.
Thinking of Selling?
What is your South Florida home worth?
Online estimates miss what makes a home different. Tell us about yours and a licensed listing agent will send you a pricing opinion based on what has actually closed near you in South Florida.
Listing agents and seller representation in South Florida
Thinking about selling in South Florida? The agent you pick shapes two numbers: what your home closes for, and how long it takes. A listing agent, also called a seller's agent, prices the property against what has actually closed nearby. They also prepare and market it, screen the offers that arrive, and negotiate the terms rather than just the price.
Conditions in South Florida sit close to balanced, which rewards sellers who price against real closed sales instead of neighboring asking prices.
South Florida is not one market. Coastal and inland behave differently, and so do new construction and 1970s stock. Condo sellers face an extra layer, because association finances and reserve funding affect what buyers can borrow.
Pure Equity is a licensed Florida brokerage serving all eight of the South Florida counties we cover. Onias Derilus is the broker of record, Florida Real Estate Broker license BK3276618. A broker holds a higher license than an agent working under one. In practice that means the person advising you on price is also the one legally responsible for the file. That matters most when a deal gets complicated.
More on this: what is an exclusive right of sale listing? · selling when you owe more than the house is worth
Realtors and real estate agents serving South Florida
People search for realtors, real estate agents, and real estate brokers more or less interchangeably. For most purposes the job title matters less than licensing and representation. Every licensed agent in Florida works under a broker. That broker carries final responsibility for the transaction.
What separates real estate professionals in South Florida is specificity. Can they answer questions about your street, not just your city? Ask what they have closed nearby and how they arrived at a price. A grounded answer cites particular recent sales. It also explains why those homes compare to yours. Vague reassurance is the warning sign.
More on this: home value after a renovation: what actually adds · how waterfront homes are valued · when and how to price your home
Buyer's agents in South Florida
A buyer's agent represents the purchaser rather than the owner. They identify properties that actually fit and research what comparable homes sold for, not what they asked. They also advise on offer strategy. Finally, they manage inspection and financing deadlines through to closing.
Where buyers have room to negotiate, as they do in South Florida, the leverage is only worth something if you know where it exists and what to ask for. If you are buying and selling at the same time, which is common for people moving within South Florida, sequencing the two is its own skill: contingencies, timing, and what happens if one closing slips all need planning before either home goes on the market.
What representation costs
Real estate commissions are negotiable. No law, multiple listing service, or association sets them. If an agent tells you there is a standard rate, they are misinforming you. What you pay is agreed between you and the brokerage you hire. Get it in writing before the work begins.
Industry rules changed in 2024. Now a buyer and their agent must put compensation in a written buyer agreement before touring homes together. Sellers may still offer to contribute toward the buyer's side. However, that is negotiated rather than assumed. It is worth thinking through with your listing agent before you go live.
More on this: how commission is actually structured · what you actually walk away with · seller concessions, and when to offer them
Buying Instead?
Search South Florida with someone local
We will tell you which listings are worth your time, what comparable homes actually closed for, and how to structure an offer that holds up through inspection and financing.
Frequently asked questions
How do I find a listing agent in South Florida?
Ask any listing agent you interview two questions. Which homes have they closed near South Florida, and how did they arrive at their suggested price? A grounded answer names recent closed sales. It also explains why those homes compare to yours. Optimistic pricing costs sellers more than almost any other decision. Verify the license too. Florida licenses are public and searchable through the state's DBPR portal. Pure Equity is a licensed brokerage serving South Florida. You can reach the broker directly at (561) 835-5400.
What does a seller's agent actually do?
A seller's agent prices the home against comparable closed sales. Before it goes live, they advise on repairs and presentation. Then they handle photography and marketing, and put the home in front of buyers and other agents. When offers arrive, they screen them and negotiate both price and terms. Terms matter as much as the number, because inspection windows, financing contingencies, and closing dates all affect whether an offer reaches the closing table.
How much does a real estate agent cost in South Florida?
Commissions are fully negotiable. No law or real estate board sets them. What you pay is whatever you and your brokerage agree to in writing before work begins. Since the 2024 rule changes, buyers and their agents must agree compensation in a written buyer agreement before touring homes. Any seller contribution toward the buyer's side is negotiated rather than automatic. Ask any agent you interview to put their fee in writing.
What is the difference between a realtor, a real estate agent, and a broker?
A real estate agent holds a state license to represent buyers and sellers. A broker holds a higher-level license and can operate a brokerage. That broker also carries final legal responsibility for the office's transactions. Realtor is a membership term for agents belonging to the National Association of Realtors. For someone buying or selling in South Florida, three practical questions matter. Is the person licensed, who do they represent in your transaction, and what can they actually tell you about your local market?
Do I need an agent to buy a home in South Florida?
You are not legally required to use one, but most buyers in South Florida do. A buyer's agent handles the parts that are easy to get wrong. That means identifying what comparable homes actually closed for, spotting condition or association issues early, and managing inspection and financing deadlines. Even in a slower market, negotiating room is only useful if you know where it exists.
Can one agent help me sell my current home and buy the next one?
Yes. For people moving within South Florida it is often the more practical route, because one person coordinates both timelines. Sequencing is the hard part. Should your purchase be contingent on your sale? How would you cover a gap if the closings do not line up? What happens if one side is delayed? Plan all of that before either home is listed, rather than after an offer arrives.
Keep Reading
More from Pure Equity
- Multi family
- New listings
- No hoa homes
- Non qm loans florida
- Oceanfront condos
- Off grid land
- Owner financing land
- Pending
- Penthouses
- Pool homes