
Homes Under $200K · Fort Lauderdale, FL
Fort Lauderdale Homes Under $200K for Sale
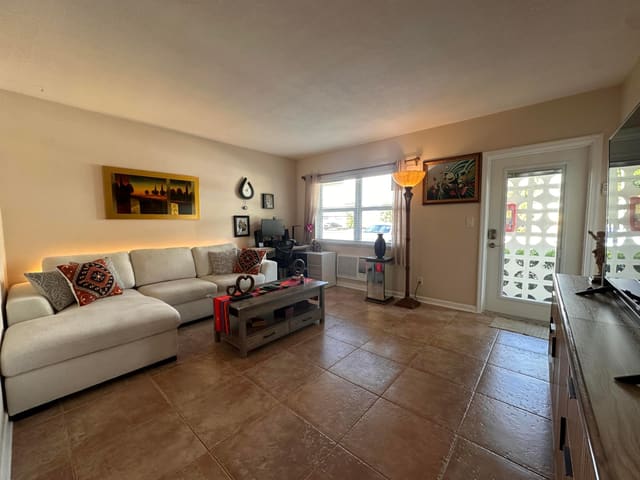
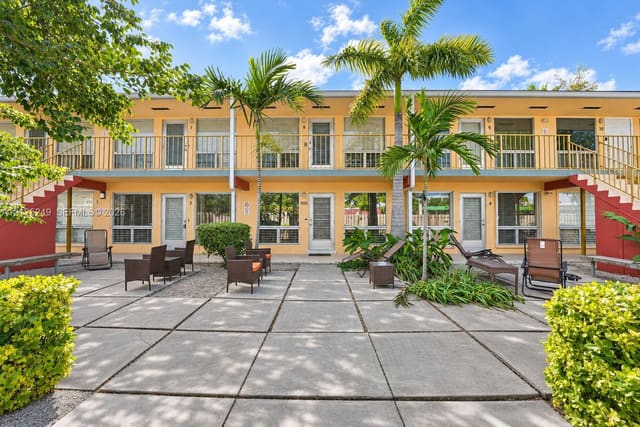
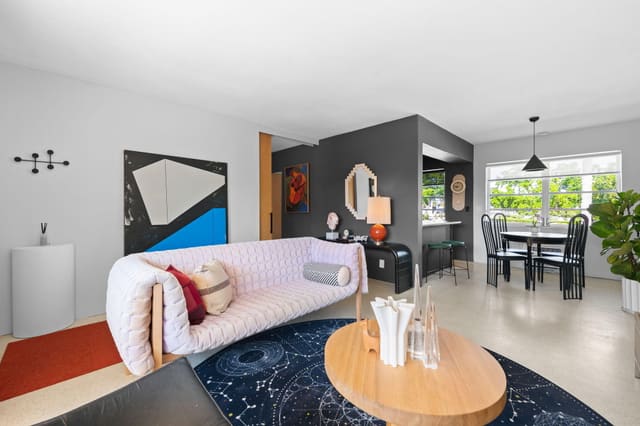
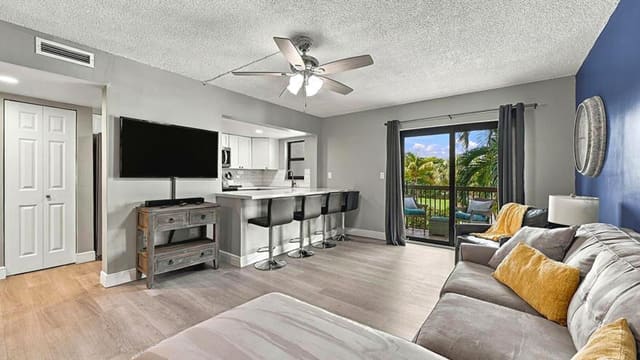
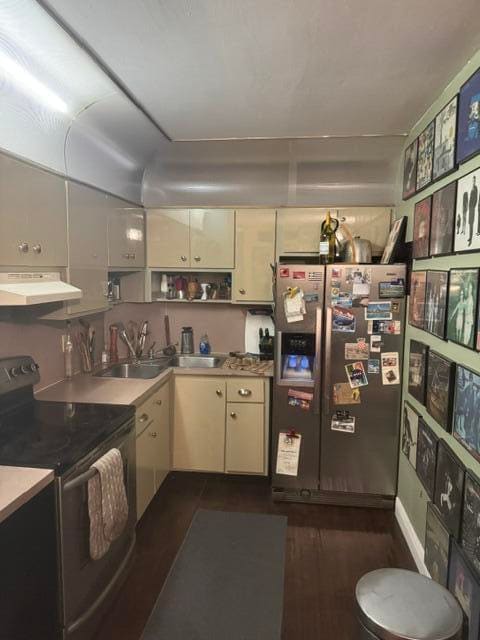
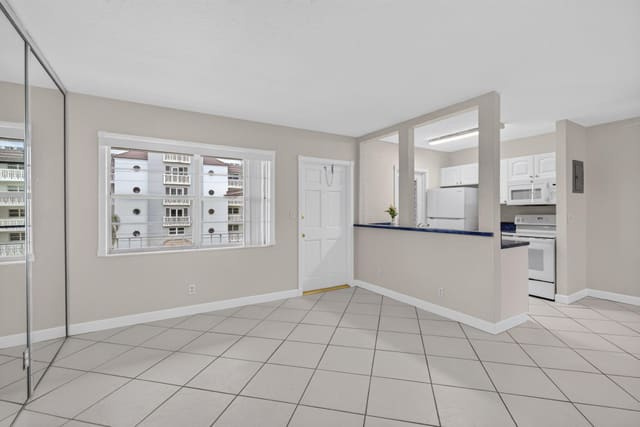
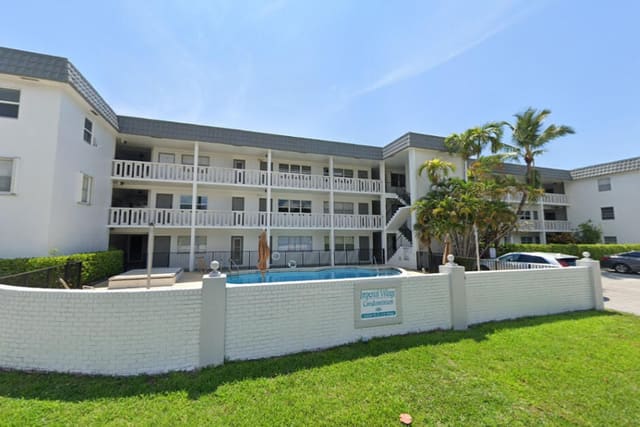
Fort Lauderdale homes under $200K are mostly small condo and co-op apartments in older buildings. In mid-November 2026 the MLS showed 180 listings in the city below that price. Of those, 149 were condos, 24 were co-ops and just 5 were houses. The median asking price was about $165,000. The median size was only about 680 square feet, so studios, efficiencies and one-bedroom units make up much of the list. The median building dates from 1970. Names that come up include Gallery One, Village at Harbor Beach, Imperial Point Colonnades, Q Club Resort and Residences, Horizon House, Maybury Mansions and Victoria Park Tower. These buildings differ in height, age and rules. Size and building type both affect what you pay each month, what a lender will allow, and how easy the unit will be to sell later.
Get Listing Alerts
Be the first to know when a new homes under $200k hits the market in Fort Lauderdale.
Available Now
Market Snapshot
The Fort Lauderdale homes under $200k market
There are 180 homes under $200k for sale in Fort Lauderdale right now, with a median list price around $158,500 among the newest listings. Inventory updates nightly from the MLS, so the homes and stats on this page track the live market.
Among the newest homes under $200k on this page, asking prices run from $119,900 to $200,000, with 1 to 2 bedroom layouts represented. The current mix leans condo and townhome, with 1 single-family home and 17 attached residences in this sample of 18. Counts shift as homes go under contract, and the full 180-listing inventory refreshes from the MLS nightly.
Local Guide
Buying homes under $200k in Fort Lauderdale
Where to look
Age is the issue to study first. Since the 2022 condo safety law, buildings of three or more stories must complete milestone structural inspections and a structural integrity reserve study. They must also fund the structural reserves the study calls for. A building from around 1970 that kept fees low for years may now need large repairs, higher dues, a special assessment or a loan the owners repay together. Ask the seller for the inspection report, the reserve study, the current budget and the last year of board minutes. Minutes often show trouble before an assessment is formally approved. Also ask whether a concrete restoration, roof or window project is underway or planned. On a 680 square foot unit, a large assessment can equal a big share of the price. Price it into your offer from the start rather than finding it at closing.
Diligence and ownership costs
Co-ops are a real share of this market, with 24 of the 180 listings, including units at Georgian Court. In a co-op you buy shares in the corporation that owns the building and receive a proprietary lease. You do not get a deed. The board usually interviews buyers, reviews their finances and can say no. It may also limit rentals, pets and how much you can borrow. Co-op loans are hard to find, so plan for cash unless a lender confirms otherwise. Condos are easier but not simple. FHA and VA loans need an approved project, and conventional lenders send a condo questionnaire about reserves, rentals and lawsuits. Some buildings near the beach run rental programs for owners' units. A lender may then treat the building as a condo-hotel, which is much harder to finance. Ask before you fall for the view.
Value, timing, and the bottom line
The 5 houses under $200,000 deserve their own caution. If you find one, ask why it is priced there. The answer may be condition, title trouble, flood history or a very small lot. Get a full inspection, a title search and a flood zone check before you commit. If you own a condo or co-op unit here, expect buyers to ask about the building first. Have the dues, the reserve study and inspection status, any assessment, the master insurance and the rental rules ready. For a co-op, explain the board process and timeline in the listing, so buyers who cannot pass it do not waste your time. Small units compete hard on condition and price, which makes recent sales in your own building the best guide. A listing agent can pull those sales and show where your unit fits.
Frequently Asked Questions
- What are Fort Lauderdale homes under $200K like?
- Mostly small condos and co-ops. In mid-November 2026, 149 of 180 listings under $200,000 were condos, 24 were co-ops and 5 were houses. The median asking price was about $165,000 and the median size about 680 square feet, so studios and one-bedroom units are common. The median building dates from 1970. That means the building's finances and inspections deserve as much attention as the unit itself.
- Which buildings have Fort Lauderdale condos under 200k?
- Buildings that show up in the listings include Gallery One, Village at Harbor Beach, Imperial Point Colonnades, Q Club Resort and Residences, Horizon House, Maybury Mansions and Victoria Park Tower. They differ a lot in age, height, amenities and rules, and rental rules vary from building to building. Compare each unit with recent sales in its own building. Then look at the dues and any coming assessment before deciding which building fits you.
- What should I know about buying a co-op in Fort Lauderdale?
- You buy shares and a proprietary lease, not a deeded unit. The board usually interviews and approves each buyer and can turn one down. Co-ops may also cap financing, limit rentals or require you to live there for a time before you can rent. Loans are hard to find, so plan on cash. Read the bylaws, the lease and the approval rules, and ask how long the board takes to decide.
- How does the 2022 condo safety law affect these buildings?
- Buildings of three or more stories must have milestone structural inspections and a structural integrity reserve study, and owners can no longer waive structural reserves. For buildings from around 1970, that can mean higher dues or special assessments. Ask for the inspection report, the study, the budget and recent minutes. On a small, low-priced unit, an assessment can be a large share of what you pay, so it belongs in your offer price.
- Can I finance a small Fort Lauderdale condo with FHA or VA?
- Only in an approved building, or one where FHA grants a single-unit approval. Conventional loans also depend on the building passing a lender's condo questionnaire, which asks about reserves, rentals, delinquent dues and lawsuits. Buildings that run like hotels, with a rental desk or pooled rental program, can face extra limits. Ask your lender to review the specific building before you write an offer, so a loan problem does not surface in the final week.
- Do I need flood insurance for a Fort Lauderdale condo?
- The association's master policy covers the structure. Your own unit owner's policy covers the interior and belongings, and flood is a separate policy. A lender will require flood coverage if the building sits in a high-risk flood zone. Even outside those zones, low-lying parts of the city can take water in heavy storms. Check the flood zone of the specific building and get quotes for both policies before your inspection period ends.
- What do buyers ask when I sell a Fort Lauderdale condo or co-op?
- They ask about the building before the unit: dues, reserves, the inspection and reserve study status, any assessment, rental rules and whether a loan is possible. For a co-op, they ask about the board and how long approval takes. Answer all of that in the listing. Order the estoppel letter early, fix what an inspector would flag, and price against recent sales in your own building rather than citywide averages.
Keep Exploring