
Homes Under $200K · Miami, FL
Miami Homes Under $200K for Sale
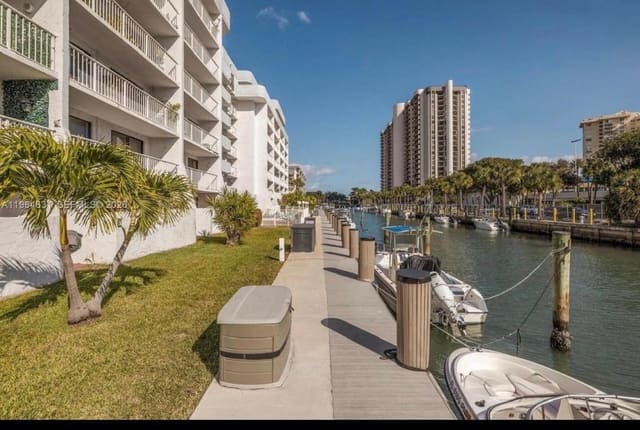
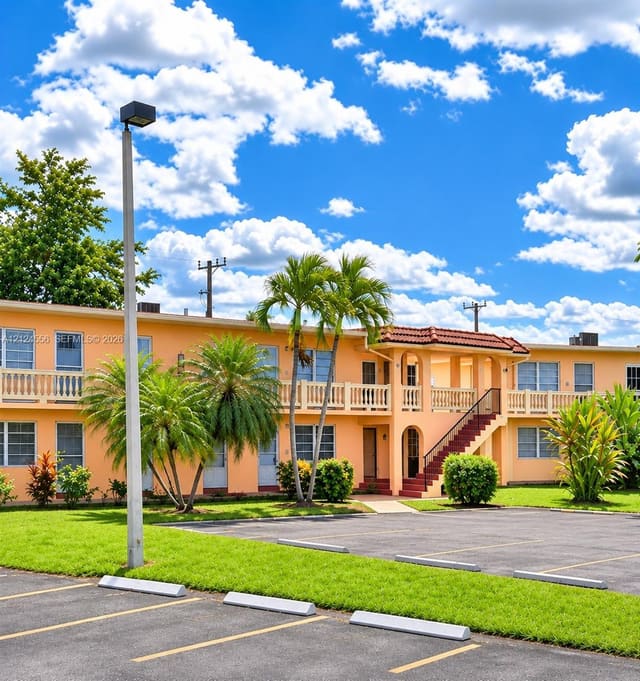
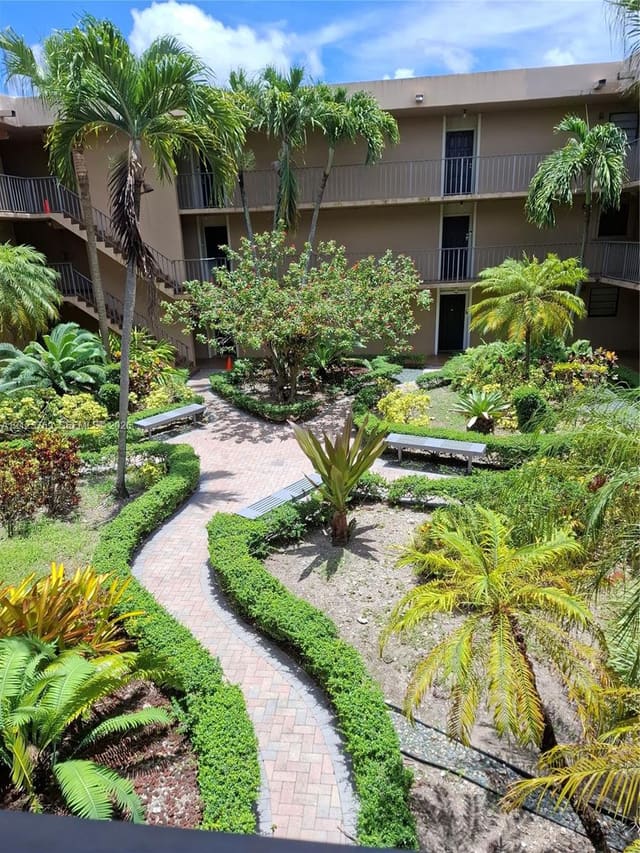
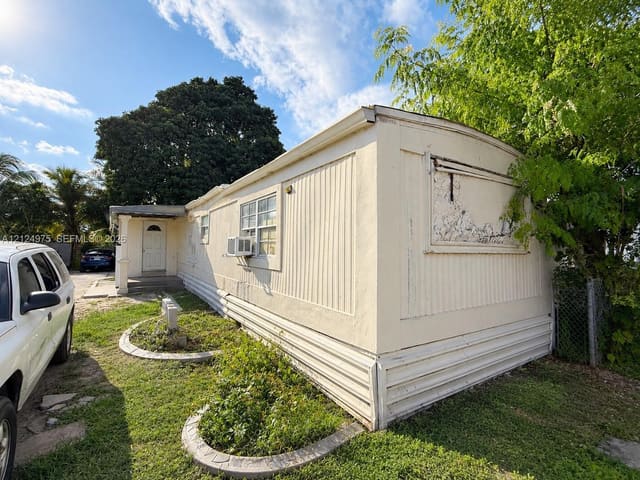
Miami homes under $200K are almost all condominium apartments, and a buyer should start from that fact. In mid-November 2026 the MLS showed 388 for-sale listings under that price with a Miami address. Of those, 344 were condos, 32 were co-ops, 7 were mobile homes and only 5 were townhouses. The median asking price was about $165,000 for a median of 830 square feet. The median building went up in 1969. So the typical listing is a one or two bedroom unit in a building more than fifty years old. That age matters more than the finishes inside. It decides what the association spends on concrete and roofs, what lenders will allow, and what insurance costs. Note too that Miami in the MLS covers many unincorporated Miami-Dade areas, such as Kendall, that carry a Miami mailing address.
Get Listing Alerts
Be the first to know when a new homes under $200k hits the market in Miami.
Available Now

Market Snapshot
The Miami homes under $200k market
There are 388 homes under $200k for sale in Miami right now, with a median list price around $159,000 among the newest listings. Inventory updates nightly from the MLS, so the homes and stats on this page track the live market.
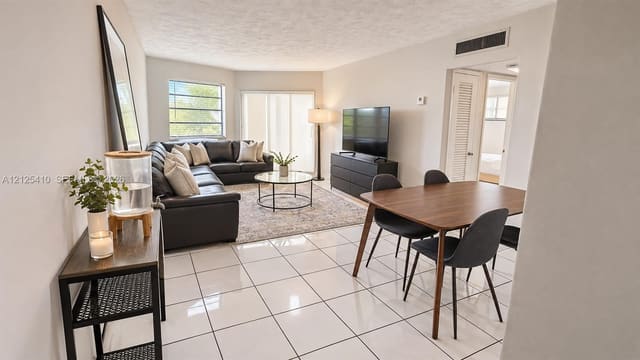
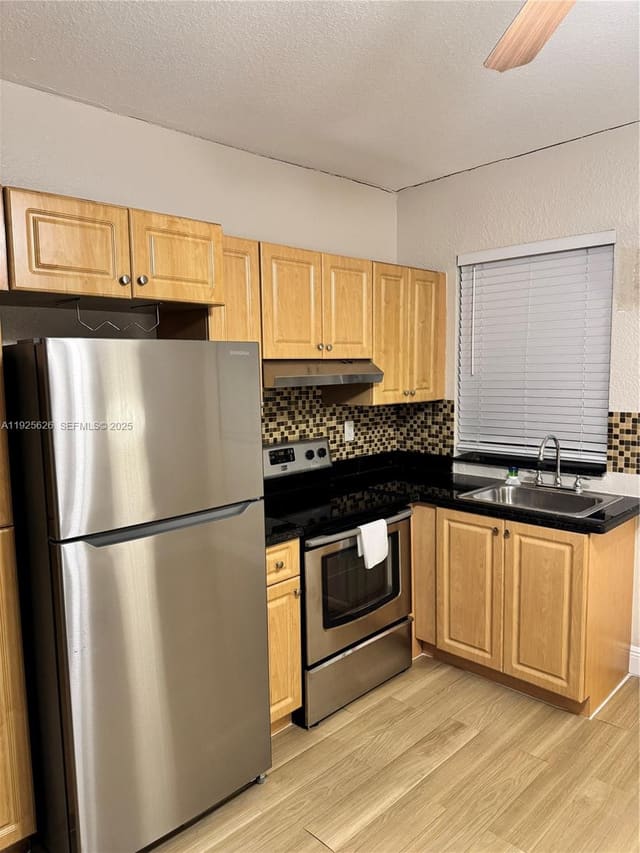
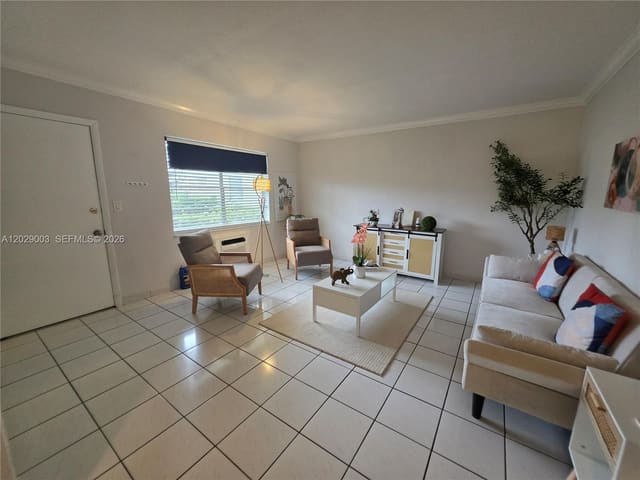
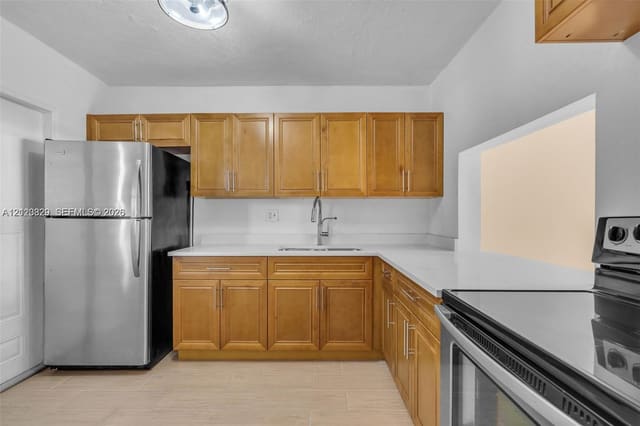
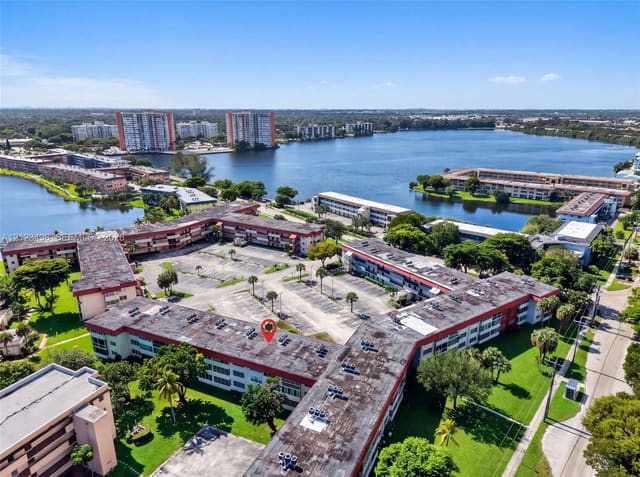
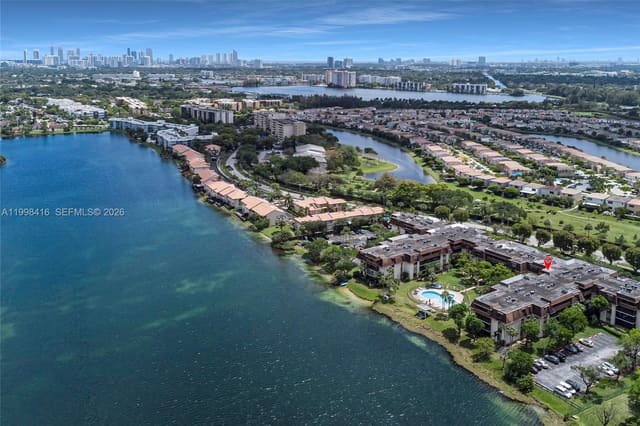
Among the newest homes under $200k on this page, asking prices run from $58,000 to $199,900, with 1 to 4 bedroom layouts represented. The current mix leans condo and townhome, with 1 single-family home and 17 attached residences in this sample of 18. Counts shift as homes go under contract, and the full 388-listing inventory refreshes from the MLS nightly.
Local Guide
Buying homes under $200k in Miami
Where to look
Building age is why the 2022 condo safety law hits this price range hardest. Since that law, condo buildings of three or more stories must pass milestone structural inspections as they age. They must also complete a structural integrity reserve study and fund the reserves it calls for. Owners can no longer vote to skip those structural reserves. For a 1960s or 1970s building that kept dues low for years, the result is often a sharp rise in monthly fees or a special assessment. Before you offer in buildings such as Buckley Towers, Point South, Jade Winds or Parkway Towers, ask for the milestone inspection report, the reserve study and the current budget. Then ask the manager in writing whether any assessment is approved or under discussion. A low price with a large assessment on the way is not a bargain.
Diligence and ownership costs
Financing is the second filter. Many older buildings do not meet lender rules, which is one reason cash is common at this price. A conventional, FHA or VA loan needs the building to qualify, not just you. FHA and VA loans work only in buildings on their approved lists, or in a unit that wins a single approval. Your lender will also send the association a condo questionnaire about reserves, litigation, rentals and unpaid dues. A building with too many renters, delinquent owners or open lawsuits can fail it late in the deal. Co-ops are a separate case. The 32 co-ops listed sell shares in a corporation plus a lease on your unit, not a deeded apartment. Expect a board interview and approval, and expect few lenders to touch them. Budget a co-op as a cash purchase unless a lender says otherwise.
Value, timing, and the bottom line
If you own a unit in this price range, your buyers are mostly cash investors, first-time buyers and retirees, and they all ask the same early questions. What are the monthly dues, and what do they include? Is a special assessment approved or likely? Has the building finished its milestone inspection and reserve study? Is it approved for FHA or VA? Gather those answers before you list. Order the association documents and the estoppel letter early, because delays there stall closings. If an assessment is coming, disclose it and price around it. Buyers will find it in the documents anyway. Units in places like Montecarlo, Yolanda Villas or Royal Oaks compete mostly with other units in the same complex. Recent sales there set your price far more than any citywide figure, so start with those before you pick a number.
Frequently Asked Questions
- What kind of Miami homes under $200K are for sale?
- Mostly condos. In mid-November 2026, 344 of the 388 listings under $200,000 were condo units, 32 were co-ops, 7 were mobile homes and 5 were townhouses. The median asking price was about $165,000 and the median size about 830 square feet. Detached houses at this price are too rare to plan a search around. If you look at one of the mobile homes, ask whether you would own the lot or pay lot rent on leased land.
- Are there Miami condos for sale under 200k?
- Yes, and they are most of this market. Names that show up often in the listings include Montecarlo, Buckley Towers, Point South, Lake Park, Jade Winds, Ola Condo and Parkway Towers. Prices inside one complex can differ a lot by floor, view, size and renovation. Compare a unit with recent sales in its own building first. Then compare the monthly dues and any pending assessment, because those can change the true cost more than the asking price does.
- Why are monthly fees rising in older Miami condo buildings?
- Mostly because of the 2022 condo safety law. Buildings of three stories and up now need milestone structural inspections and a structural integrity reserve study, and owners can no longer waive the structural reserves. Buildings that kept dues low for decades now have to fund roofs, concrete repair and other major items. Ask for the reserve study and the budget before you offer. Also ask whether a special assessment has been approved or proposed.
- Can I use an FHA or VA loan on a Miami condo?
- Only if the building qualifies. FHA and VA keep lists of approved condo projects, and FHA can sometimes approve a single unit in a building that is not on its list. Conventional lenders also review the building through a condo questionnaire that asks about reserves, rentals, delinquencies and lawsuits. Many older buildings fail one of those tests. Check the building's status with your lender before you write an offer, not after.
- How is buying a co-op different from buying a condo?
- With a co-op you buy shares in the corporation that owns the building, plus a proprietary lease on your unit. You do not get a deed to the apartment. The board usually interviews and approves buyers, and it can set rules on renting, pets and financing. Co-ops are harder to finance than condos, so plan on paying cash unless a lender confirms a loan in writing. Read the bylaws and the approval rules before you commit.
- What insurance does a Miami condo owner need?
- The association carries a master policy on the structure. You carry a unit owner's policy, often called an HO-6, for your interior, belongings and liability. Premiums depend on the building's age, roof, wind protection and flood zone, and older buildings near the water usually cost more to insure. Get a quote on the specific unit during your inspection period. Ask about the master policy deductible too, since owners can be assessed for it after a storm.
- How do I sell a Miami condo priced under $200K?
- Start with the building, not the unit. Buyers and lenders will ask for the dues, the reserve study, the milestone inspection status, any special assessment and whether the building is FHA or VA approved. Have those answers ready, and order the estoppel letter early. Then price against recent sales in your own complex. A clean, well-documented listing usually sells sooner than a cheaper one that leaves buyers with open questions.
Keep Exploring