
South Florida
Oceanfront Condos for Sale Under $200,000 in Florida
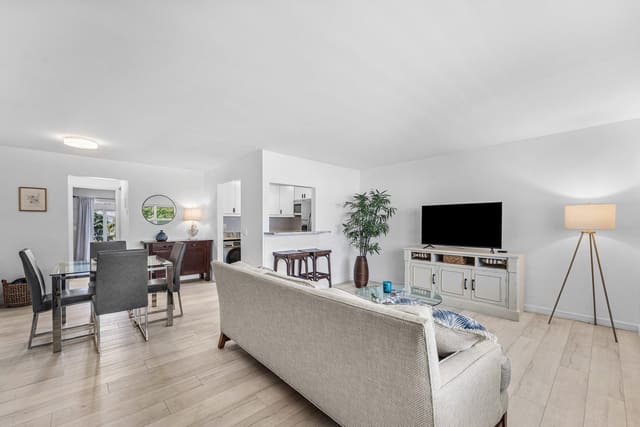
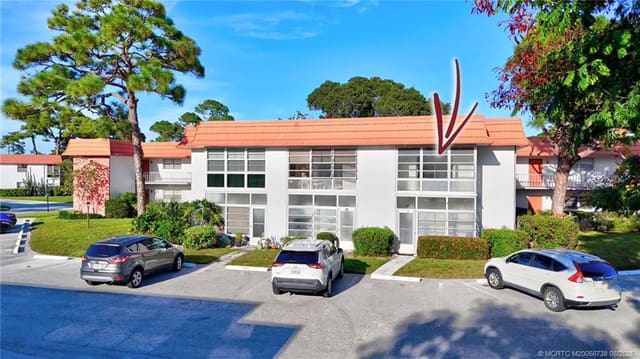
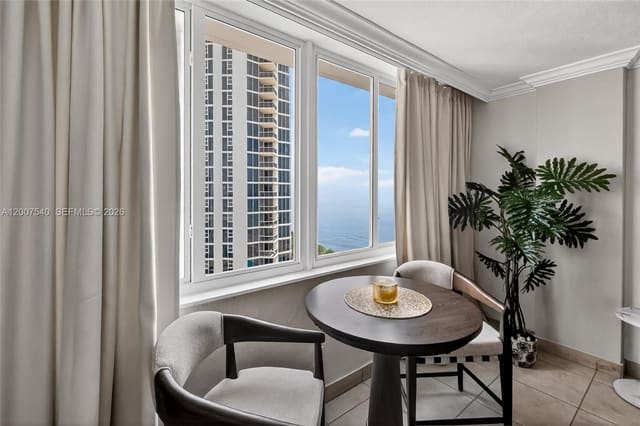
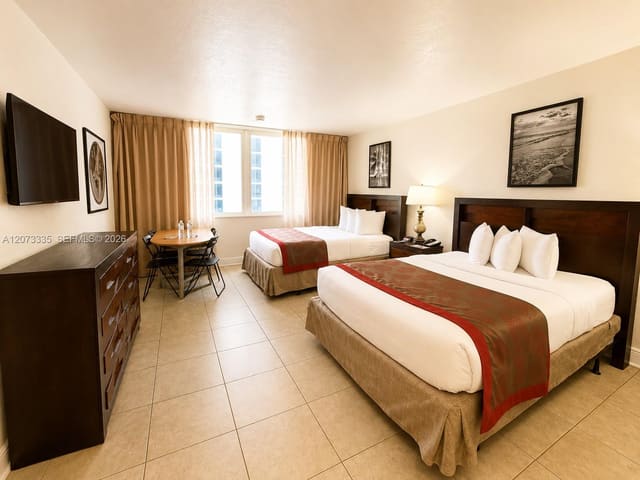
Oceanfront and ocean-view condos and co-ops listed at $200,000 or less, mostly in older towers in Sunny Isles Beach, Fort Lauderdale, Fort Pierce and Pompano Beach.
Get Listings Alerts
Be the first to know when a new oceanfront condos under $200k listing hits the market in South Florida.
Browse
Oceanfront Condos Under $200K in South Florida
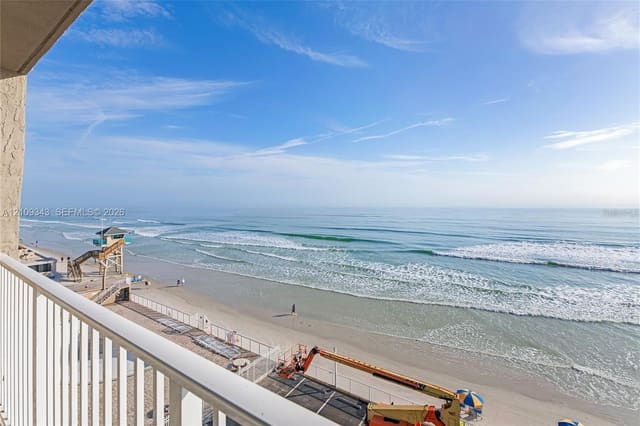
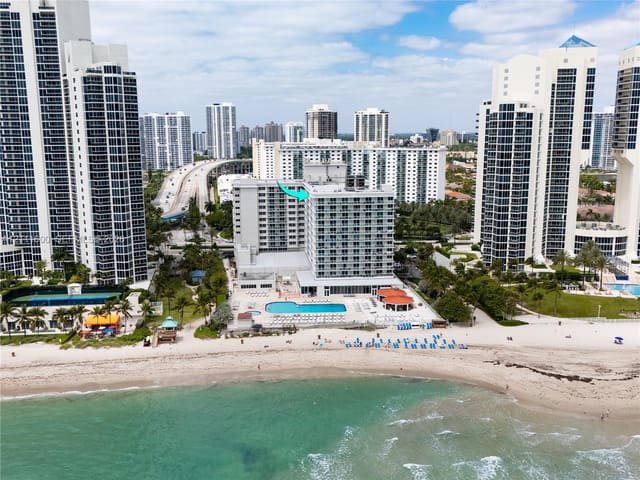
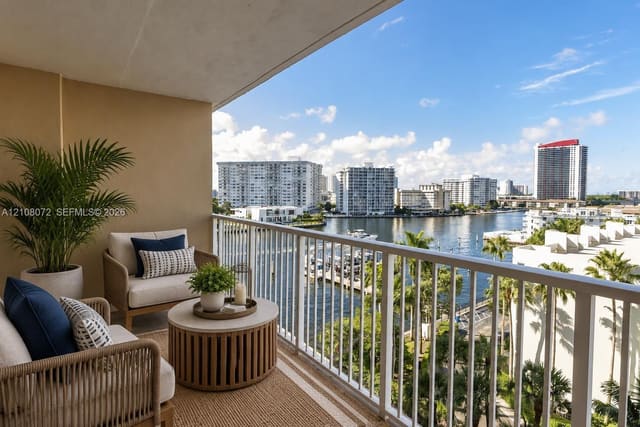
Stay Ahead of the Market
Tell us what you're looking for and we'll send matches as they hit the market.
Explore by County
Featured Communities
Oceanfront Condos Under $200K in South Florida
What oceanfront condos under 200k look like today
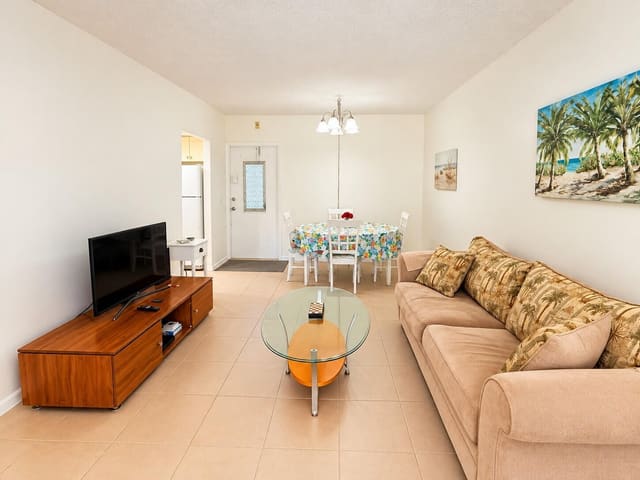
In mid-November 2026 we counted 106 active listings in this price range. Of those, 97 were condominiums and 9 were cooperative apartments. The median list price was $150,000. The cheapest asked about $70,000 and the most expensive asked $199,999, right at the ceiling. That spread tells you something. At the low end you are often looking at a small studio or a co-op share, while units close to $200,000 tend to be one-bedrooms with more space.
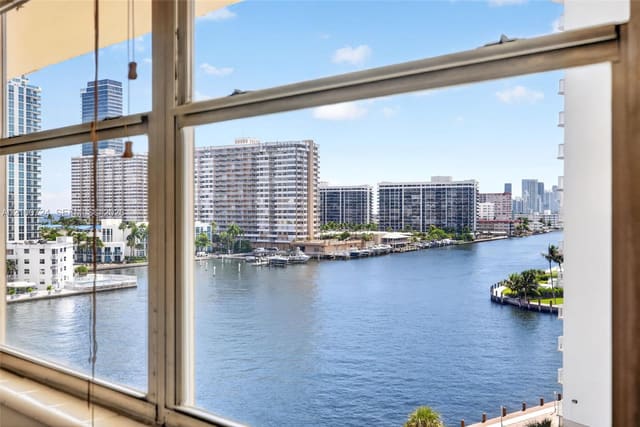
One caution before you start scrolling. The filter includes listings that say "ocean view" as well as those that say oceanfront. So not every unit here is in a building directly on the sand. Some sit across a road, behind another tower, or a block back with a side view of the water. Always confirm where the building stands and which way the unit faces before you fall for the photos.
Where the cheapest oceanfront condos are
Sunny Isles Beach dominates this list, with 50 of the 106 listings in mid-November 2026. Fort Lauderdale came next with 11, then Fort Pierce with 7 and Pompano Beach with 5. Hollywood, Boynton Beach, Daytona Beach, Hallandale Beach and Miami Beach each had 4. South Palm Beach, Deerfield Beach and Aventura each had 2.
By county, Miami-Dade held 58 listings and Broward held 28. Palm Beach and St. Lucie had 7 each, Volusia had 5 and Martin had 1. In short, the deepest supply is on the Miami-Dade and Broward coast, where large towers from the 1960s and 1970s put hundreds of units on a single stretch of beach. The Treasure Coast and Volusia offer fewer units but often a quieter setting.
Why most of these buildings are older
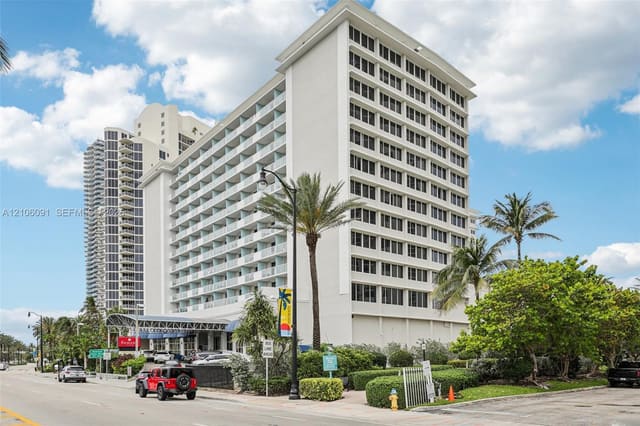
The median year built across these listings was 1966. That is not an accident. Newer oceanfront towers rarely have units priced this low, so the affordable end of the market is mostly older stock. Many of these buildings were put up before modern rules on coastal construction took full shape.
Today, Florida's Coastal Construction Control Line governs building seaward of that line. New construction and major work near the beach face stricter standards than many of these buildings were originally held to. Older buildings can be perfectly sound, and plenty are well kept. Still, age brings real questions about concrete, balconies, roofs, windows and plumbing. Salt air speeds up wear on all of it, so the condition of the building matters as much as the unit.
The 2022 condo safety law and what it means for you
After the Surfside collapse, Florida passed a condo safety law in 2022. It requires milestone structural inspections for condo buildings three stories or taller. It also requires those associations to complete a structural integrity reserve study. That study covers major parts of the building and sets the money the association needs to set aside for them.
For a buyer of an older oceanfront unit, this matters a great deal. A building that put off repairs for years may now need to raise dues or levy a special assessment to catch up. We cannot tell you what any one building owes, because that depends on its own reports. What we can say is that the inspection report, the reserve study and the board minutes belong at the top of your reading list. On an older tower by the ocean, the list price is only part of the cost.
Selling an oceanfront condo under 200k
If you own one of these units, you are selling into a narrow market with very specific buyers. Most are retirees, snowbirds, second-home buyers and cash investors. They want the water, but they also want proof that the building is not hiding a problem. Owners who have the association's milestone inspection, reserve study, budget and recent minutes ready to share tend to field fewer surprises once a contract is signed.
Expect buyers to ask the same handful of questions. Is there a special assessment coming? Can I rent it, and for how long? Are pets allowed? Is the building approved for conventional or FHA financing? Is the view direct or partial? Clear answers make a cheaper unit easier to sell, because they remove the doubt that drives low offers.
Pricing is the other half of the job. Compare your unit to recent sales in the same building first, then to nearby towers of a similar age. Your view, your floor and the state of your kitchen and bath all move the number. Commission is negotiable, and we will walk you through the options. Start with a free valuation so you know where you stand.
Condo or co-op: know which one you are buying
Nine of the 106 listings in mid-November 2026 were co-ops, and the difference is not just a label. When you buy a condo, you own your unit outright plus a share of the common areas. When you buy a co-op, you buy shares in a corporation that owns the building, and you get the right to live in your unit.
A co-op purchase needs board approval, so the board can turn a buyer down. Co-ops can also be harder to finance, because many lenders do not make loans on co-op shares. That smaller pool of lenders and buyers is part of why some co-op units are priced lower. If a listing looks unusually cheap for its location, check whether it is a co-op before you plan your financing.
Financing, insurance and flood zones
Condo financing depends on the building as a whole, not just your unit. Lenders look at the association's reserves, its insurance, any pending litigation and the share of units that are rented. A building that falls short of their standards can push buyers toward a larger down payment or a cash purchase. Ask early whether the building is approved for the loan type you plan to use.
Location by the ocean also brings flood questions. Lenders require flood insurance on properties in high-risk FEMA flood zones, and many beach buildings sit in those zones. The association usually insures the building itself, while you insure the inside of your unit and your belongings. Get insurance quotes during your inspection period, not after closing, so the full monthly cost is clear before you commit.
How to shop this list well
Start with the building, not the unit. Pull up the association documents, read the inspection and reserve study, and ask about any planned work. Then check the rules on rentals, pets and minimum lease terms, since many oceanfront associations limit or ban short stays. If you need income from the unit, those rules decide whether the numbers work at all.
Next, confirm the view in person or by video. A listing that says ocean view may mean a sliver of water past a parking lot. Look at the balcony, the windows and the hallways, because they show how the building has been kept. Finally, compare a few towers side by side. Two units at the same price can carry very different costs once dues, assessments and insurance are added in.
Questions
Oceanfront Condos Under $200K: Frequently asked questions
Can you still buy an oceanfront condo in Florida for under $200,000?
Yes, but the choice is limited. In mid-November 2026 our MLS feed showed 106 active condo and co-op listings at or below $200,000 whose descriptions mention oceanfront, beachfront or ocean view. The median asking price was $150,000. Most were in older buildings, and about half were in Sunny Isles Beach. Expect smaller units, older finishes and buildings that need close review of their reports and reserves.
Where are the most oceanfront condos under $200,000?
Sunny Isles Beach had the most by a wide margin, with 50 listings in mid-November 2026. Fort Lauderdale had 11 and Fort Pierce had 7, followed by Pompano Beach with 5. By county, Miami-Dade led with 58 and Broward had 28. Palm Beach and St. Lucie had 7 each. These counts change daily as units sell and new ones list, so check the live listings above for today's supply.
Is every condo on this page directly on the beach?
No. The filter includes listings that mention ocean view as well as oceanfront and beachfront. Some buildings sit directly on the sand, while others are across a road or a block back with a partial view. Confirm the building's position on a map and check the unit's actual view before making an offer. A direct-ocean unit and a side-view unit in the same area can be very different purchases.
Why are oceanfront condos this cheap?
Most are in older buildings, with a median build year of 1966 across these listings. Many are small units, and some are co-ops, which need board approval and can be harder to finance. Older buildings may also face repair costs under Florida's 2022 condo safety law. Those factors keep prices lower than newer towers. A low price can be fair value, but it can also signal costs that come later.
What does the 2022 condo safety law require?
It requires milestone structural inspections for condo buildings three stories or taller. It also requires those associations to complete a structural integrity reserve study, which sets the money needed for major building components. For buyers, the effect is practical. Buildings that underfunded repairs may raise dues or levy special assessments. Read the inspection report, the reserve study and recent board minutes before you sign a contract.
Do I need flood insurance for an oceanfront condo?
If you use a mortgage and the property is in a high-risk FEMA flood zone, your lender will require flood insurance. Many beachfront buildings fall in those zones. The association typically insures the structure, and you cover your unit's interior and belongings. Even if you pay cash, flood coverage is worth pricing. Get quotes during your inspection period so the full cost of ownership is known before closing.
I own an oceanfront condo. How do I get the best price when I sell?
Gather the association's milestone inspection, reserve study, budget and recent minutes before you list, because buyers in this range will ask for them. Be ready to answer questions about assessments, rental rules, pets and financing approval. Price against recent sales in your own building first. Commission is negotiable. A free valuation from a local listing agent is a good first step to see where your unit stands.
Related Reading
Oceanfront Condos Under $200K: From the Journal
Home Buying Tips · October 1, 2026
Oceanfront Condos Near Jupiter Island and Hobe Sound: What Buyers Should Ask Before Making an Offer
Where Jupiter Island's oceanfront condos really sit, why the Martin and Palm Beach county line matters, and the reserve, inspection, rental, insurance and flood questions to ask before you make an offer.
Home Buying Tips · October 1, 2026
Noise in Florida Condos and Townhomes: Soundproofing Rules, Flooring Underlayment and What to Check Before You Buy
A buyer's guide to neighbor noise in Palm Beach County condos and townhomes: the building code standard, underlayment rules, construction types, showing tests and the documents to read before closing.
Mortgage & Rates · October 1, 2026
Mortgage Underwriting in Florida: How Long It Takes, What Can Withdraw an Approval and Why Sellers Should Care
Underwriting is where a buyer's loan approval is won or lost. See typical timelines, the deadlines in the Florida contract, what can pull an approval late, and how sellers can judge a buyer's financing.
Thinking of Selling?
What is your South Florida home worth?
Online estimates miss what makes a home different. Tell us about yours and a licensed listing agent will send you a pricing opinion based on what has actually closed near you in South Florida.
Listing agents and seller representation in South Florida
Thinking about selling in South Florida? The agent you pick shapes two numbers: what your home closes for, and how long it takes. A listing agent, also called a seller's agent, prices the property against what has actually closed nearby. They also prepare and market it, screen the offers that arrive, and negotiate the terms rather than just the price.
Conditions in South Florida sit close to balanced, which rewards sellers who price against real closed sales instead of neighboring asking prices.
South Florida is not one market. Coastal and inland behave differently, and so do new construction and 1970s stock. Condo sellers face an extra layer, because association finances and reserve funding affect what buyers can borrow.
Pure Equity is a licensed Florida brokerage serving all eight of the South Florida counties we cover. Onias Derilus is the broker of record, Florida Real Estate Broker license BK3276618. A broker holds a higher license than an agent working under one. In practice that means the person advising you on price is also the one legally responsible for the file. That matters most when a deal gets complicated.
More on this: what is an exclusive right of sale listing? · selling when you owe more than the house is worth
Realtors and real estate agents serving South Florida
People search for realtors, real estate agents, and real estate brokers more or less interchangeably. For most purposes the job title matters less than licensing and representation. Every licensed agent in Florida works under a broker. That broker carries final responsibility for the transaction.
What separates real estate professionals in South Florida is specificity. Can they answer questions about your street, not just your city? Ask what they have closed nearby and how they arrived at a price. A grounded answer cites particular recent sales. It also explains why those homes compare to yours. Vague reassurance is the warning sign.
More on this: home value after a renovation: what actually adds · how waterfront homes are valued · when and how to price your home
Buyer's agents in South Florida
A buyer's agent represents the purchaser rather than the owner. They identify properties that actually fit and research what comparable homes sold for, not what they asked. They also advise on offer strategy. Finally, they manage inspection and financing deadlines through to closing.
Where buyers have room to negotiate, as they do in South Florida, the leverage is only worth something if you know where it exists and what to ask for. If you are buying and selling at the same time, which is common for people moving within South Florida, sequencing the two is its own skill: contingencies, timing, and what happens if one closing slips all need planning before either home goes on the market.
What representation costs
Real estate commissions are negotiable. No law, multiple listing service, or association sets them. If an agent tells you there is a standard rate, they are misinforming you. What you pay is agreed between you and the brokerage you hire. Get it in writing before the work begins.
Industry rules changed in 2024. Now a buyer and their agent must put compensation in a written buyer agreement before touring homes together. Sellers may still offer to contribute toward the buyer's side. However, that is negotiated rather than assumed. It is worth thinking through with your listing agent before you go live.
More on this: how commission is actually structured · what you actually walk away with · seller concessions, and when to offer them
Buying Instead?
Search South Florida with someone local
We will tell you which listings are worth your time, what comparable homes actually closed for, and how to structure an offer that holds up through inspection and financing.
Frequently asked questions
How do I find a listing agent in South Florida?
Ask any listing agent you interview two questions. Which homes have they closed near South Florida, and how did they arrive at their suggested price? A grounded answer names recent closed sales. It also explains why those homes compare to yours. Optimistic pricing costs sellers more than almost any other decision. Verify the license too. Florida licenses are public and searchable through the state's DBPR portal. Pure Equity is a licensed brokerage serving South Florida. You can reach the broker directly at (561) 835-5400.
What does a seller's agent actually do?
A seller's agent prices the home against comparable closed sales. Before it goes live, they advise on repairs and presentation. Then they handle photography and marketing, and put the home in front of buyers and other agents. When offers arrive, they screen them and negotiate both price and terms. Terms matter as much as the number, because inspection windows, financing contingencies, and closing dates all affect whether an offer reaches the closing table.
How much does a real estate agent cost in South Florida?
Commissions are fully negotiable. No law or real estate board sets them. What you pay is whatever you and your brokerage agree to in writing before work begins. Since the 2024 rule changes, buyers and their agents must agree compensation in a written buyer agreement before touring homes. Any seller contribution toward the buyer's side is negotiated rather than automatic. Ask any agent you interview to put their fee in writing.
What is the difference between a realtor, a real estate agent, and a broker?
A real estate agent holds a state license to represent buyers and sellers. A broker holds a higher-level license and can operate a brokerage. That broker also carries final legal responsibility for the office's transactions. Realtor is a membership term for agents belonging to the National Association of Realtors. For someone buying or selling in South Florida, three practical questions matter. Is the person licensed, who do they represent in your transaction, and what can they actually tell you about your local market?
Do I need an agent to buy a home in South Florida?
You are not legally required to use one, but most buyers in South Florida do. A buyer's agent handles the parts that are easy to get wrong. That means identifying what comparable homes actually closed for, spotting condition or association issues early, and managing inspection and financing deadlines. Even in a slower market, negotiating room is only useful if you know where it exists.
Can one agent help me sell my current home and buy the next one?
Yes. For people moving within South Florida it is often the more practical route, because one person coordinates both timelines. Sequencing is the hard part. Should your purchase be contingent on your sale? How would you cover a gap if the closings do not line up? What happens if one side is delayed? Plan all of that before either home is listed, rather than after an offer arrives.
Keep Reading
More from Pure Equity
- Oceanfront homes under 300k
- Off grid land
- Owner financed homes
- Owner financing land
- Pending
- Penthouses
- Pool homes
- Preparing to sell your home
- Price reduced
- Probate real estate agent in Florida: selling an inherited house