
Multi-Family Homes · Hialeah, FL
Hialeah Multi-Family Homes for Sale
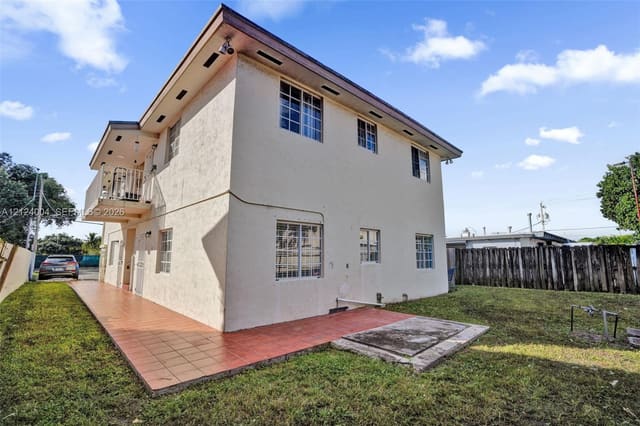
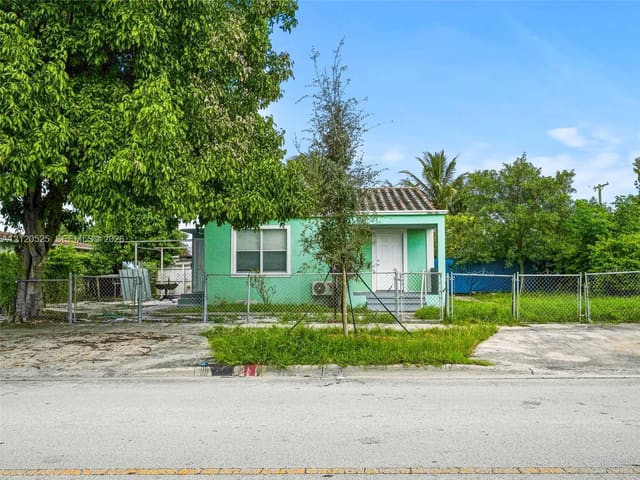
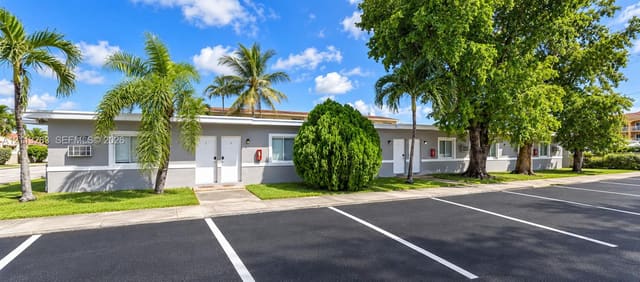
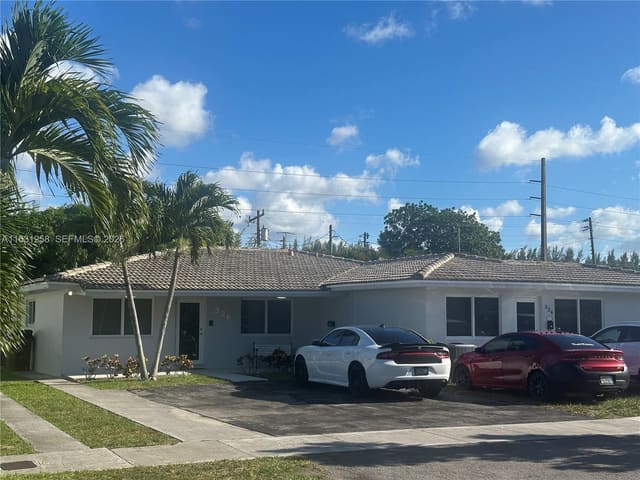
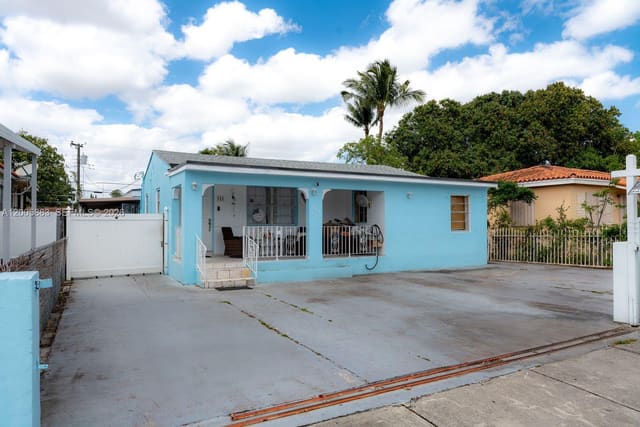
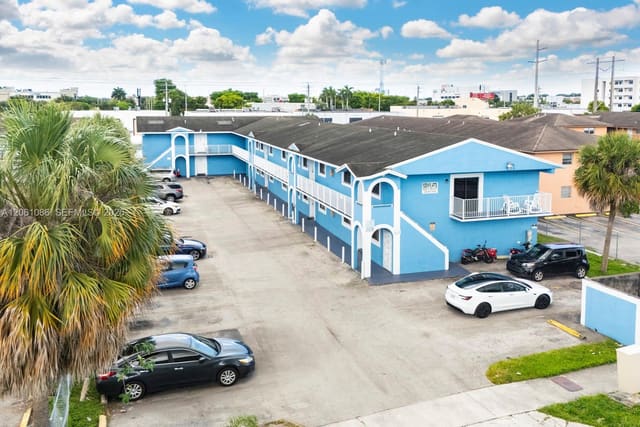
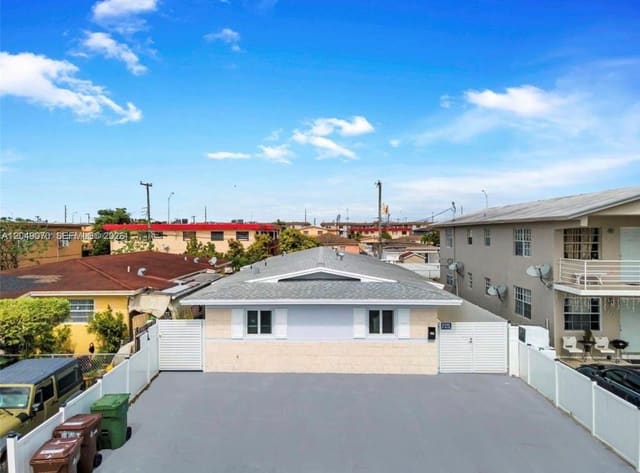
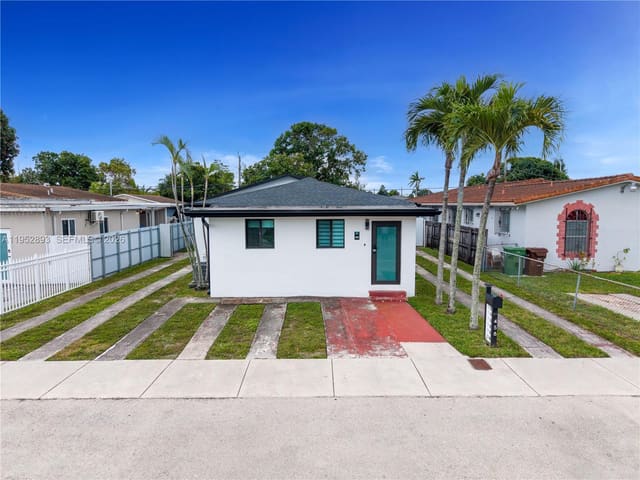
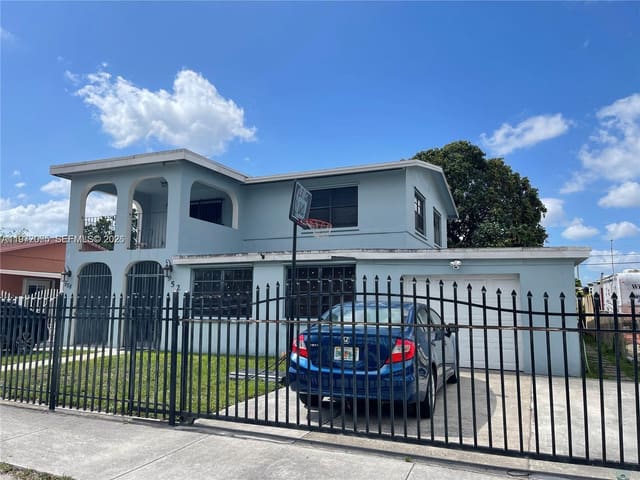
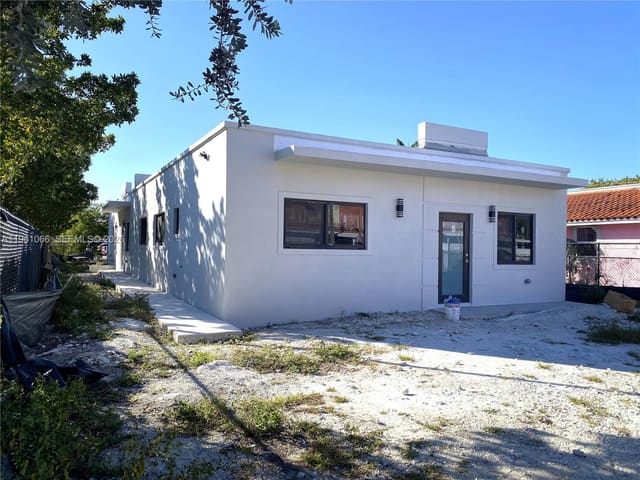
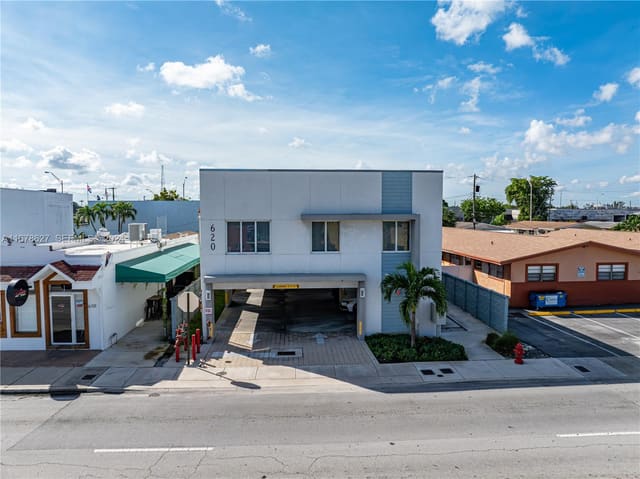
Hialeah multi-family homes are scarce on the market, and it is better to know that up front. In mid-November 2026 the MLS showed only 17 for sale in the city: 12 duplexes, 4 quadruplexes and 1 triplex. Asking prices ran from about $523,000 to $3.7 million, with a median near $885,000. The median building dates from 1952, though the newest was built in 2025. The buildings run larger than in many nearby cities, with a median of about 2,519 square feet across all units. With so few choices, you cannot shop a wide field. You will likely see a building, compare it to a handful of others and decide. That rewards buyers who have financing settled and know what they need before a listing appears. Set an alert and watch recent sales too, since they tell you more than a short list of active listings.
Get Listing Alerts
Be the first to know when a new multi-family home hits the market in Hialeah.
Available Now
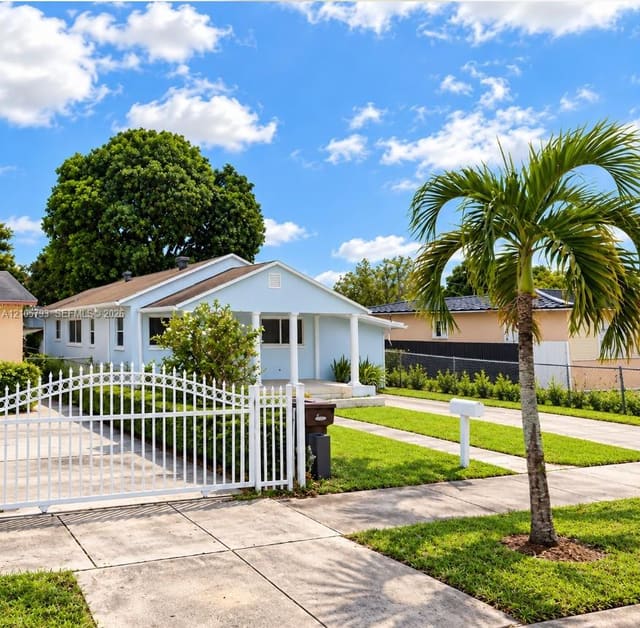
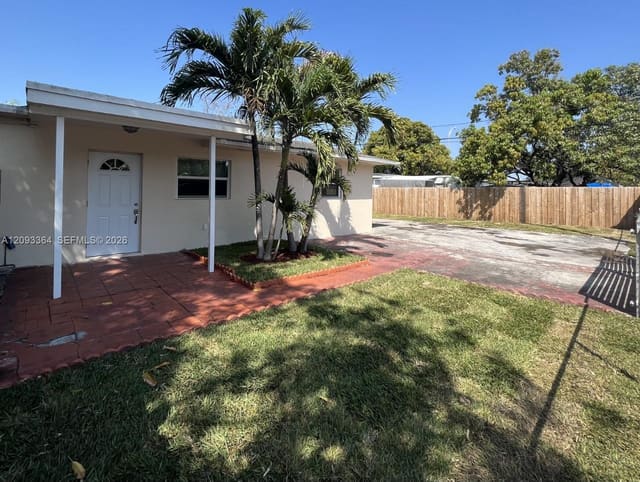
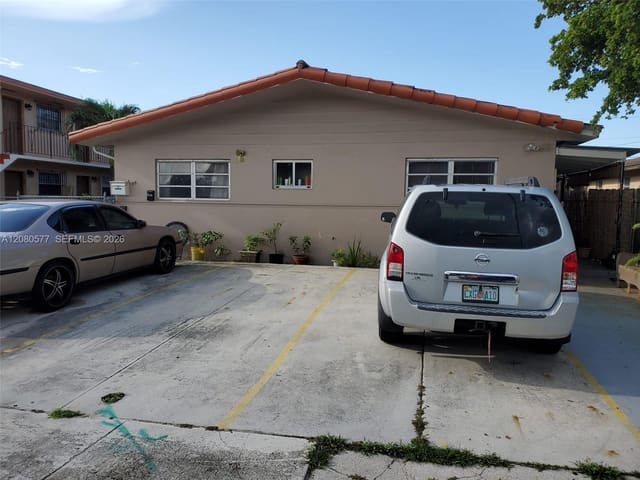
Market Snapshot
The Hialeah multi-family homes market
There are 17 multi-family homes for sale in Hialeah right now, with a median list price around $1,099,000 among the newest listings. Inventory updates nightly from the MLS, so the homes and stats on this page track the live market.
Among the newest multi-family homes on this page, asking prices run from $522,722 to $3,700,000, with 5 to 5 bedroom layouts represented. The current mix leans single-family, with 0 single-family homes and 0 attached residences in this sample of 16. Counts shift as homes go under contract, and the full 17-listing inventory refreshes from the MLS nightly.
Local Guide
Buying multi-family homes in Hialeah
Where to look
Your loan decides which buildings you can chase. If you will live in one unit, an FHA loan can cover a 2 to 4 unit building with a low down payment. One unit must be your main home. On a quad, FHA also checks that the building's rent can carry the payment, so a vacant unit can be a problem. Conventional owner-occupied loans are another option for 2 to 4 units. Investors who will not live on site usually use a conventional investment loan or a DSCR loan. A DSCR lender looks mostly at whether the rent covers the debt. Both investor loans need more money down. With this little inventory, get preapproved before you look. A seller with one strong offer in hand will not wait while your lender reviews the file.
Diligence and ownership costs
Verify the legal unit count with care. Converted garages and added efficiencies are a common issue in older Miami-Dade housing, and a unit without permits can mean lost rent and a code case. Compare what you see with the permit history and the city's zoning, since Hialeah has its own code. Check that each unit has a separate electric meter. On a building from the early 1950s, look at the roof, the electrical panel and the drain lines, which may be original cast iron. Insurance carriers usually want a four-point inspection on a building that age. Check the flood zone and get a flood quote as well as a property quote. Read every lease and match each deposit to it. If a lease is written in Spanish and you do not read it, have it translated before you rely on it.
Value, timing, and the bottom line
The listings were in the numbered Hialeah additions and in plats such as Palm Avenue Lawns, Seminola City and Susan Gardens. If you own a small building here and plan to sell, short supply works in your favor only if the building is ready. Buyers searching residential income properties for sale Hialeah will ask for a rent roll on the first call. Have it ready with signed leases, a deposit ledger and a year of expenses. Pull your permit history and close anything still open, especially for any unit that was added or converted. Note the ages of the roof, panel and water heaters. Tell tenants that estoppel letters and showings are coming. A clean, complete file lets a buyer's lender move on schedule, and it gives you a stronger position when you negotiate the price.
Frequently Asked Questions
- How much do hialeah multi-family homes cost?
- In mid-November 2026, the 17 listings asked from about $523,000 to $3.7 million, with a median near $885,000. Most were duplexes. With so few listings, one large building can pull the range up, so look at price per unit and at recent sales. The buildings are fairly large, with a median of about 2,519 square feet. Ask how many units are leased right now. The live listings on this page show what is available today.
- Why are so few multi-family buildings for sale in Hialeah?
- At the time of writing, only 17 were listed. We do not have data on why. What matters for a buyer is the effect: you have little to compare, and good buildings can draw several offers. Get preapproved, set up a listing alert, and study recent sales and pending deals. That gives you a better sense of value than the active list alone. Be ready to move within days.
- Can I live in one unit of a Hialeah duplex and rent the other?
- Yes. An FHA or conventional owner-occupied loan on a 2 to 4 unit building expects exactly that. You must move into one unit and use it as your main home. Lenders can usually count part of the rent from the other unit when qualifying you. The building has to meet the lender's property standards, so an older duplex may need repairs first. Get the lender's list of required repairs early.
- How do I spot an unpermitted unit?
- Compare the units you see with the permit history and the recorded use on the property record. A garage with a kitchen, an extra meter, or a separate door at the back of the house are common signs of a conversion. Ask the seller directly and in writing. If a unit is not legal, a lender may not count its rent, and the city may order it removed.
- What does a DSCR loan mean for a Hialeah investor?
- A DSCR loan qualifies the building mostly on its rent compared with the loan payment, rather than on your personal income. It can help investors who own several properties or who are self-employed. Expect a larger down payment and a higher rate than an owner-occupied loan. Ask each lender how it treats a vacant or unpermitted unit, since either can sink the ratio. Compare at least two or three lenders.
- What insurance checks does an older building need?
- On a building from the 1950s, carriers usually ask for a four-point inspection covering the roof, electrical, plumbing and air conditioning. A wind mitigation report may lower the premium. Flood coverage is a separate policy based on the FEMA flood zone, and lenders require it in high-risk zones. Get quotes for both during your inspection period, before your deposit is at risk. Share the quotes with your lender too.
- What should a Hialeah owner prepare before selling?
- A rent roll, signed leases, a deposit ledger, a year of expenses and the full permit history. If any unit was added or converted, have its permits ready or expect questions. List the ages of the roof, panels and water heaters. Tell tenants that estoppel letters are coming. With so few buildings on the market, a complete file helps a buyer commit faster. It also shows the building has nothing to hide.
Keep Exploring